Borr Drilling Ltd/$BORR
1D1W1MYTD1Y5YMAX
Capital at risk
About Borr Drilling Ltd
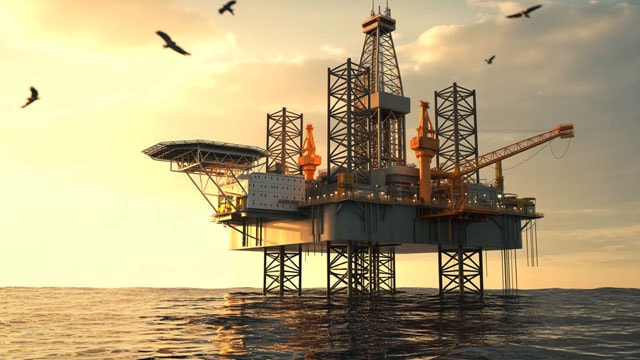
Borr Drilling Ltd is an offshore shallow-water drilling contractor providing services to the oil and gas industry. Its operations focus on the ownership, contracting, and operation of jack-up rigs in shallow-water areas, including the provision of related equipment and work crews to conduct oil and gas drilling and workover operations for exploration and production (E&P) customers. The company contracts its rigs on a dayrate basis to drill wells for integrated oil companies, state-owned national oil companies, and independent oil and gas companies. It operates in one reportable segment.
- Ticker
- $BORR
- Sector
- Energy
- Primary listing
- NYSE
- Employees
- 2,030
- Headquarters
- Hamilton, Bermuda
- Website
- borrdrilling.com
BORR Metrics
BasicAdvanced
$1.4B
-
-$0.83
1.01
-
Price and volume
Market cap
$1.4B
Beta
1.01
52-week high
$6.66
52-week low
$2.44
Average daily volume
6.2M
Financial strength
Current ratio
2.532
Quick ratio
2.338
Long term debt to equity
2.585
Total debt to equity
2.586
Interest coverage (TTM)
0.90%
Profitability
EBITDA (TTM)
373.1
Gross margin (TTM)
43.68%
Net profit margin (TTM)
-23.98%
Operating margin (TTM)
20.84%
Effective tax rate (TTM)
-22.97%
Revenue per employee (TTM)
$500,000
Management effectiveness
Return on assets (TTM)
3.75%
Return on equity (TTM)
-24.68%
Valuation
Price to revenue (TTM)
1.298
Price to book
1.43
Price to tangible book (TTM)
1.43
Price to free cash flow (TTM)
-9.155
Free cash flow yield (TTM)
-10.92%
Free cash flow per share (TTM)
-0.487
Growth
Revenue change (TTM)
2.71%
Earnings per share change (TTM)
-517.90%
3-year revenue growth (CAGR)
18.14%
3-year earnings per share growth (CAGR)
30.43%
Bulls say / Bears say
Contract visibility improved substantially: Borr reported 21 contract commitments year-to-date through June 2026, representing approximately 4,350 days and $541 million of Dayrate Equivalent Backlog; total backlog reached $1.13 billion as of August 11. (SEC filing)
Fleet utilization remained strong, with Q2 technical utilization of 98.4% and economic utilization of 96.4%; management also expected approximately 23 active rigs in Q3 as contract transitions largely concluded. (SEC filing)
The refinancing extended maturities, reduced financing costs, increased the revolving credit facility to $250 million, and was followed by the completion of a 50/50 joint venture acquisition of five premium jack-up rigs—expanding Borr’s fleet and potential revenue base with limited direct equity committed. (SEC filing)
Q2 2026 operating momentum weakened: revenue fell 6% sequentially to $232.3 million and Adjusted EBITDA dropped 51% to $43.8 million, partly reflecting fewer operating rigs and contract-transition activity. (SEC filing)
Execution risk remains material: the Odin’s delayed start-up required $22.5 million of Q2 operating expenses and postponed revenue generation, highlighting the cost and timing risks of mobilizing rigs into new markets. (SEC filing)
The balance sheet remains highly leveraged despite refinancing: Borr issued approximately $2.035 billion of senior secured notes and $300 million of convertible notes, creating continuing interest obligations and potential equity dilution. (SEC filing)
Data summarised monthly by Lightyear AI. Last updated on 8 Sept 2026.
Upcoming events
No upcoming events
BORR News
AllArticlesVideos
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.