Five Below/$FIVE
1D1W1M3M6MYTD1Y5YMAX
Capital at risk
About Five Below
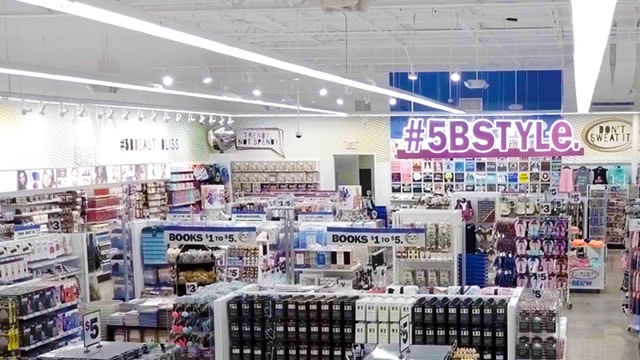
Five Below Inc is a specialty value retailer offering a broad range of trend-right, high-quality products loved by the kid and the kid in all of customers. The Company's edited assortment of products includes select brands and licensed merchandise. The Company also sells its merchandise on the internet, through the Company's e-commerce website and mobile app, offering home delivery and the option to buy online and pick up in store. Additionally, the Company sells merchandise through on-demand third-party delivery services to enable its customers to shop online and receive convenient delivery. It derives revenue from sales of the Company's merchandise to customers.
- Ticker
- $FIVE
- Sector
- Consumer Discretionary
- Primary listing
- NASDAQ
- Employees
- 16,200
- Headquarters
- Philadelphia, United States
- Website
- www.fivebelow.com
Five Below Metrics
BasicAdvanced
$13B
21.63
$11.14
0.99
-
Price and volume
Market cap
$13B
Beta
0.99
52-week high
$263.88
52-week low
$143.02
Average daily volume
950K
Financial strength
Current ratio
2.222
Quick ratio
1.181
Long term debt to equity
0.699
Total debt to equity
0.823
Profitability
EBITDA (TTM)
815.272
Gross margin (TTM)
37.09%
Net profit margin (TTM)
11.65%
Operating margin (TTM)
11.67%
Effective tax rate (TTM)
24.42%
Revenue per employee (TTM)
$330,000
Management effectiveness
Return on assets (TTM)
7.84%
Return on equity (TTM)
28.25%
Valuation
Price to earnings (TTM)
21.629
Price to revenue (TTM)
2.502
Price to book
5.36
Price to tangible book (TTM)
5.36
Price to free cash flow (TTM)
22.188
Free cash flow yield (TTM)
4.51%
Free cash flow per share (TTM)
10.86
Growth
Revenue change (TTM)
25.56%
Earnings per share change (TTM)
125.17%
3-year revenue growth (CAGR)
17.77%
10-year revenue growth (CAGR)
19.31%
3-year earnings per share growth (CAGR)
31.77%
10-year earnings per share growth (CAGR)
25.62%
What the Analysts think about Five Below
Analyst ratings (Buy, Hold, Sell) for Five Below stock.
Analyst projections of the future price of Five Below stock.
Bulls say / Bears say
Comparable sales rose 14.1% in Q2, the fifth straight quarter of double-digit growth, and sales grew 22.9%. Five Below also raised its full-year sales and comparable-sales outlook, supporting the case that customer demand remains strong. (Five Below, Bloomberg)
Store openings add another growth engine: Five Below opened 52 net new shops in Q2 and plans about 150 for the year. Management says it sees room to grow to more than 3,500 US stores, with new shops delivering 12–15-month returns. (Five Below, StockAnalysis)
Profitability is improving alongside sales: Q2 adjusted operating income more than doubled year on year, and the company raised its full-year adjusted EPS forecast to $9.83–$10.31. This suggests the recovery is not relying on sales growth alone. (Five Below)
Q2 GAAP profit included a $169.5 million pre-tax benefit from tariff refunds. That one-off boost makes headline earnings growth look stronger than the recurring business alone. (SEC)
Comparable-sales growth slowed from 22.7% in Q1 to 14.1% in Q2, and the company expects 8%–10% in Q3. Tougher year-on-year comparisons could make it harder to sustain the recent pace. (Five Below, The Motley Fool)
Costs could erode margin gains: Five Below says higher fuel costs have already increased distribution expenses, while its reliance on imported goods leaves it exposed to tariff changes. Such costs may be harder to pass on without weakening its value appeal. (SEC)
Data summarised monthly by Lightyear AI. Last updated on 29 Oct 2026.
Five Below Financial Performance
Revenues and expenses
Five Below Earnings Performance
Company profitability
Upcoming events
No upcoming events
Five Below News
AllArticlesVideos
Funds containing Five Below
AllUSDEURGBP
Fund name | Fund size | $FIVE weighting |
|---|---|---|
SPDR S&P 400 US Mid Cap$SPY4 | $6.4B | 0.39% |
SPDR S&P 400 US Mid Cap£SPX4 | $6.4B | 0.39% |
iShares MSCI USA Small Cap ESG Enhanced CTB€SXRG | $3.2B | 0.24% |
iShares MSCI USA Small Cap CTB Enhanced ESG£CUS1 | $3.2B | 0.24% |
iShares MSCI World Small Cap£WLDS | $9B | 0.13% |
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.