Mayville Engineering Company/$MEC
1D1W1M3M6MYTD1Y5YMAX
Capital at risk
About Mayville Engineering Company
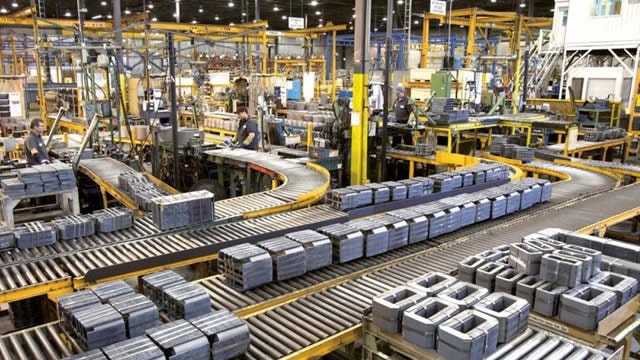
Mayville Engineering Co Inc is involved in a manufacturing partner providing a full suite of manufacturing solutions from concept to production, including design, prototyping and tooling, fabrication, aluminum extrusion, coating, assembly, and aftermarket components. Its customers operate in diverse end markets, including heavy- and medium-duty commercial vehicles, construction, powersports, agriculture, military, and other end markets. Its services comprise stamping, shearing, fiber laser cutting, forming, drilling, tapping, grinding, tube bending, machining, welding, assembly, and logistic services.
- Ticker
- $MEC
- Sector
- Industrials
- Primary listing
- NYSE
- Employees
- 2,400
- Headquarters
- Milwaukee, United States
- Website
- www.mecinc.com
MEC Metrics
BasicAdvanced
$358M
-
-$0.64
1.49
-
Price and volume
Market cap
$358M
Beta
1.49
52-week high
$38.76
52-week low
$12.42
Average daily volume
525K
Financial strength
Current ratio
1.741
Quick ratio
0.901
Long term debt to equity
0.504
Total debt to equity
0.525
Interest coverage (TTM)
-0.12%
Profitability
EBITDA (TTM)
42.766
Gross margin (TTM)
10.73%
Net profit margin (TTM)
-2.32%
Operating margin (TTM)
-0.28%
Effective tax rate (TTM)
37.02%
Revenue per employee (TTM)
$260,000
Management effectiveness
Return on assets (TTM)
-0.18%
Return on equity (TTM)
-4.97%
Valuation
Price to revenue (TTM)
0.511
Price to book
1.09
Price to tangible book (TTM)
4.21
Price to free cash flow (TTM)
-46.179
Free cash flow yield (TTM)
-2.17%
Free cash flow per share (TTM)
-0.304
Growth
Revenue change (TTM)
14.78%
Earnings per share change (TTM)
-209.47%
3-year revenue growth (CAGR)
2.52%
3-year earnings per share growth (CAGR)
18.86%
What the Analysts think about MEC
Analyst ratings (Buy, Hold, Sell) for Mayville Engineering Company stock.
Analyst projections of the future price of Mayville Engineering Company stock.
Bulls say / Bears say
Datacenter and critical power is becoming a meaningful growth engine: sales rose 64.9% in Q3 to $37.2 million, MEC won about $45 million of new projects and its qualified pipeline exceeded $200 million. This gives it a sizable opportunity to keep growing as more programmes ramp. (MEC Inc.)
MEC is investing ahead of demand, with its Thomson, Georgia facility expected to add about $50 million of annual revenue capacity by 2028. Management expects existing capacity to be full within 18 months, so the expansion could help it convert new awards into sales rather than turn away work. (MEC Inc.)
The Q3 upturn reached beyond data centres: revenue rose 18.1% year on year, while adjusted EBITDA margin improved 190 basis points sequentially to 10%. Commercial vehicle sales increased 34.7%, alongside a 9.3% rise in construction and access sales, suggesting recovery in these markets is supporting utilisation. (MEC Inc.)
The data-centre ramp is not yet translating cleanly into profit: about $20 million of project volume was pushed into early 2027, and MEC expects Q4 adjusted EBITDA margin to be below Q3. Launch, outsourcing and premium labour costs are also weighing on near-term returns. (The Motley Fool)
Weak legacy demand is leaving parts of MEC’s factory base underused. Q3 sales fell 26.9% in powersports and 9.9% in agriculture, and management said powersports softness is likely to continue into 2027. (MEC Inc.)
Cash generation and leverage leave less room for execution setbacks: MEC forecast full-year free cash flow of negative $6 million to negative $16 million, compared with positive $26.9 million in 2025, while net debt was $146.6 million and leverage stood at 2.9 times. Planned capital spending of $25 million to $35 million adds to the funding burden. (SEC)
Data summarised monthly by Lightyear AI. Last updated on 6 Nov 2026.
MEC Financial Performance
Revenues and expenses
MEC Earnings Performance
Company profitability
Upcoming events
No upcoming events
MEC News
AllArticlesVideos
Funds containing MEC
Fund name | Fund size | $MEC weighting |
|---|---|---|
SPDR Russell 2000 US Small Cap€R2US | $5B | 0.01% |
SPDR Russell 2000 US Small Cap£R2SC | $5B | 0.01% |
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.