Polaris/$PII
1D1W1M3M6MYTD1Y5YMAX
Capital at risk
About Polaris
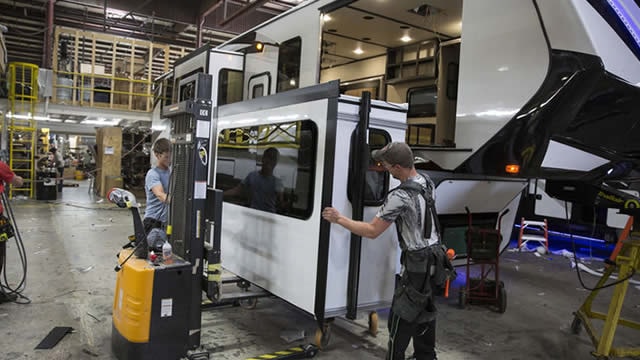
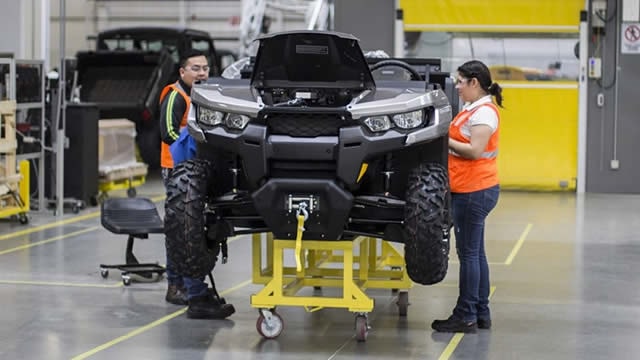
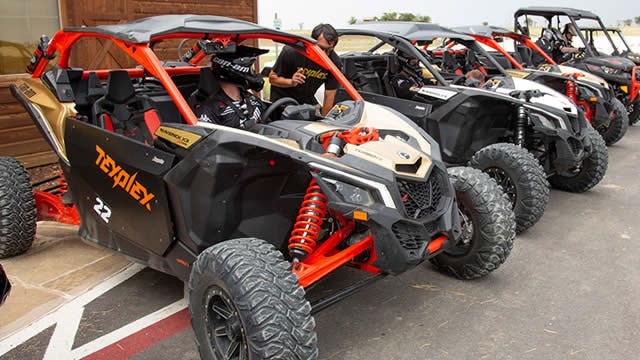
Polaris designs and manufactures off-road vehicles, including all-terrain vehicles and side-by-side vehicles for recreational, utility, military, and commercial purposes, snowmobiles, and on-road vehicles, along with the related replacement parts, garments, and accessories. The firm entered the marine market after acquiring Boat Holdings in 2018, offering exposure to pontoon and deck boat users. It divested its Indian motorcycle brand to Carolwood in early 2026. Polaris products are retailed through more than 2,500 dealers in North America and 1,500 international dealers as well as more than 25 subsidiaries and 90 distributors in more than 100 countries outside North America.
- Ticker
- $PII
- Sector
- Consumer Discretionary
- Primary listing
- NYSE
- Employees
- 14,500
- Headquarters
- Medina, United States
- Website
- www.polaris.com
Polaris Metrics
BasicAdvanced
$3.8B
-
-$3.60
1.34
$2.71
4.10%
Price and volume
Market cap
$3.8B
Beta
1.34
52-week high
$77.98
52-week low
$47.14
Average daily volume
862K
Dividend rate
$2.71
Financial strength
Current ratio
1.064
Quick ratio
0.262
Long term debt to equity
2
Total debt to equity
2.071
Interest coverage (TTM)
1.82%
Profitability
EBITDA (TTM)
488.5
Gross margin (TTM)
22.02%
Net profit margin (TTM)
-2.67%
Operating margin (TTM)
2.91%
Effective tax rate (TTM)
8.76%
Revenue per employee (TTM)
$530,000
Management effectiveness
Return on assets (TTM)
2.85%
Return on equity (TTM)
-20.50%
Valuation
Price to revenue (TTM)
0.493
Price to book
4.47
Price to tangible book (TTM)
64.09
Price to free cash flow (TTM)
14.33
Free cash flow yield (TTM)
6.98%
Free cash flow per share (TTM)
4.629
Dividend yield (TTM)
4.09%
Forward dividend yield
4.10%
Growth
Revenue change (TTM)
9.03%
Earnings per share change (TTM)
34.99%
3-year revenue growth (CAGR)
-5.43%
10-year revenue growth (CAGR)
5.58%
3-year earnings per share growth (CAGR)
-29.44%
10-year earnings per share growth (CAGR)
-0.98%
3-year dividend per share growth (CAGR)
1.52%
10-year dividend per share growth (CAGR)
2.20%
What the Analysts think about Polaris
Analyst ratings (Buy, Hold, Sell) for Polaris stock.
Analyst projections of the future price of Polaris stock.
Bulls say / Bears say
Polaris gained ORV market share for a sixth straight quarter. North American utility ORV retail rose 6% and total ORV retail rose 2%, while the wider market was flat. (SEC)
The operating recovery is showing through beyond the headline tariff benefit: operational adjusted EPS rose to $0.95 from $0.41 a year earlier, while adjusted EBITDA margin expanded to 8.8%. Management raised its full-year operational EPS outlook to $2.40–$2.50. (The Motley Fool)
Polaris strengthened its balance sheet, cutting debt by more than $320 million in the quarter and lowering net leverage to 2.0 times from 3.4 times at the start of 2026. That gives it more room to invest and manage a cyclical downturn. (The Motley Fool)
The raised 2026 adjusted EPS outlook includes $1.09 per share from tariff refunds, so the headline forecast overstates the run-rate earnings investors can expect without those benefits. (SEC)
Some Q3 earnings were pulled forward: management said about $0.30 per share shifted from Q4 into Q3. It expects roughly flat Q4 organic sales and adjusted EPS of just $0.32–$0.42. (The Motley Fool)
The margin rebound still faces pressure from roughly $70 million of higher commodity and logistics costs, while recreational demand remains soft and pontoon retail was down by a low-double-digit rate. That mix could make further earnings improvement harder to sustain. (The Motley Fool)
Data summarised monthly by Lightyear AI. Last updated on 9 Nov 2026.
Polaris Financial Performance
Revenues and expenses
Polaris Earnings Performance
Company profitability
Upcoming events
Polaris News
AllArticlesVideos
Funds containing Polaris
AllUSDEURGBP
Fund name | Fund size | $PII weighting |
|---|---|---|
iShares Ageing Population€AGED | $887M | 0.31% |
iShares Ageing Population£AGES | $887M | 0.31% |
iShares Ageing Population$AGED | $953M | 0.31% |
SPDR S&P US Dividend Aristocrats£USDV | $3.6B | 0.14% |
SPDR S&P US Dividend Aristocrats€SPYD | $3.6B | 0.14% |
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.