Commercial Metals/$CMC
1D1W1M3M6MYTD1Y5YMAX
Capital at risk
About Commercial Metals
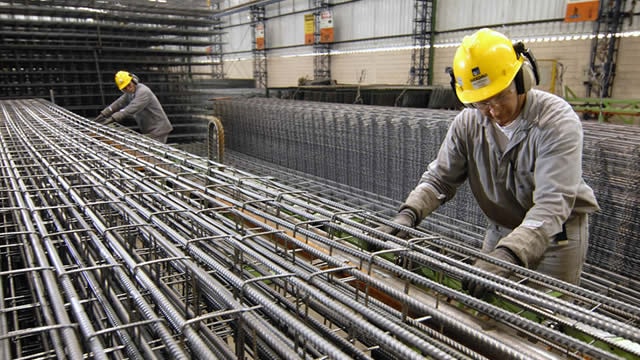
Commercial Metals Co is a manufacturer and supplier of early-stage construction materials, including steel reinforcing bars, concrete pipes, precast products, and soil stabilization solutions. It also produces merchant bar, steel fence posts, and wire rod, serving domestic and some international markets in Europe and Asia. Its products are used in infrastructure and building projects such as highways, bridges, airports, and commercial and residential buildings.
- Ticker
- $CMC
- Sector
- Materials
- Primary listing
- NYSE
- Employees
- 12,690
- Headquarters
- Irving, United States
- Website
- www.cmc.com
CMC Metrics
BasicAdvanced
$7.2B
11.09
$5.86
1.53
$0.76
1.23%
Price and volume
Market cap
$7.2B
Beta
1.53
52-week high
$84.87
52-week low
$55.70
Average daily volume
1.2M
Dividend rate
$0.76
Financial strength
Current ratio
2.339
Quick ratio
1.442
Long term debt to equity
0.705
Total debt to equity
0.72
Dividend payout ratio (TTM)
12.85%
Interest coverage (TTM)
6.07%
Profitability
EBITDA (TTM)
1,265.646
Gross margin (TTM)
18.65%
Net profit margin (TTM)
6.98%
Operating margin (TTM)
9.26%
Effective tax rate (TTM)
7.76%
Revenue per employee (TTM)
$740,000
Management effectiveness
Return on assets (TTM)
6.24%
Return on equity (TTM)
14.75%
Valuation
Price to earnings (TTM)
11.089
Price to revenue (TTM)
0.767
Price to book
1.53
Price to tangible book (TTM)
3.37
Price to free cash flow (TTM)
15.035
Free cash flow yield (TTM)
6.65%
Free cash flow per share (TTM)
4.322
Dividend yield (TTM)
1.17%
Forward dividend yield
1.23%
Growth
Revenue change (TTM)
20.46%
Earnings per share change (TTM)
691.89%
3-year revenue growth (CAGR)
2.20%
10-year revenue growth (CAGR)
10.08%
3-year earnings per share growth (CAGR)
-6.85%
10-year earnings per share growth (CAGR)
28.76%
3-year dividend per share growth (CAGR)
5.90%
10-year dividend per share growth (CAGR)
4.70%
What the Analysts think about CMC
Analyst ratings (Buy, Hold, Sell) for Commercial Metals stock.
Analyst projections of the future price of Commercial Metals stock.
Bulls say / Bears say
Third-quarter core EBITDA rose 78.6% year on year to $353.6 million, while the margin widened by 440 basis points to 14.2%. That shows CMC is converting stronger market conditions and its efficiency programme into higher profitability. (CMC)
The precast acquisitions helped Construction Solutions nearly double sales and lift adjusted EBITDA by 138% in the third quarter. This expands CMC’s higher-value construction offering beyond steel and contributed $52.9 million of segment EBITDA in the quarter. (CMC)
At its August investor day, CMC set a 2029 core EBITDA target of $1.65 billion to $1.8 billion and said free cash flow could reach $1.4 billion to $1.5 billion from 2027. The targets give investors a potential growth path if the company delivers on its efficiency, investment and portfolio plans. (EarningsCalls.dev, PR Newswire)
CMC needs a sharp sequential earnings lift in the fourth quarter after outages, wet weather and higher scrap costs weighed on North American steel in the third quarter. Management’s expected $40 million to $50 million EBITDA increase leaves little room for another operational setback. (Earnings Whispers, CMC)
Steel margins could come under pressure if imports or new US mill capacity limit selling prices. CMC’s latest filing identifies imports and additional domestic steelmaking capacity as risks, while recent reporting notes rising imports and new rebar capacity. (SEC, Earnings Whispers)
The precast business faces a delivery test: recent reporting says backlog growth slowed and the full-year EBITDA target now requires a strong fourth-quarter catch-up. Missing that target would weaken the case that the acquisitions can provide dependable growth beyond steel. (Earnings Whispers, CMC)
Data summarised monthly by Lightyear AI. Last updated on 12 Oct 2026.
CMC Financial Performance
Revenues and expenses
CMC Earnings Performance
Company profitability
Upcoming events
CMC News
AllArticlesVideos
Funds containing CMC
AllEURGBPUSD
Fund name | Fund size | $CMC weighting |
|---|---|---|
iShares MSCI USA Small Cap ESG Enhanced CTB€SXRG | €2.8B | 0.34% |
iShares MSCI USA Small Cap CTB Enhanced ESG£CUS1 | £2.4B | 0.34% |
SPDR Russell 2000 US Small Cap€R2US | €4.8B | 0.25% |
SPDR Russell 2000 US Small Cap£R2SC | £4.1B | 0.25% |
SPDR S&P 400 US Mid Cap$SPY4 | $6.3B | 0.21% |
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.