J.M. Smucker/$SJM
1D1W1MYTD1Y5YMAX
Capital at risk
About J.M. Smucker
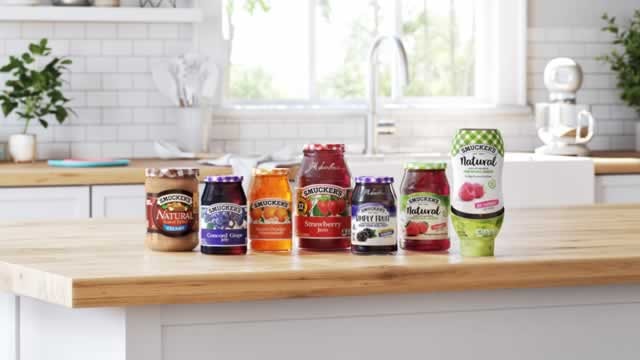
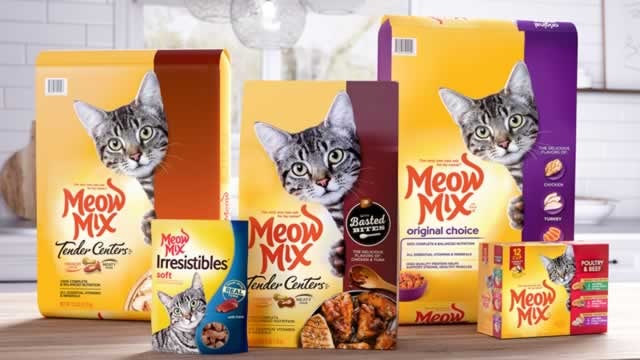
J.M. Smucker is a packaged food company that primarily sells through the US retail channel (75% of fiscal 2026 revenue came through its retail pet foods, coffee, and frozen handheld/spreads segments), with the remaining share consisting of sweet baked snacks (through the Hostess acquisition), away from home, and international (primarily Canada). Retail coffee is its largest category (37% of sales) with brands Folgers, Dunkin', and Cafe Bustelo. Pet foods (18% of sales) holds leading brands like Milk-Bone and Meow Mix. Of its remaining, approximately 20% comes from frozen handhelds and spreads, through brands Jif, Smucker's, and Uncrustables. The company acquired Hostess Brands in fiscal 2024 to boost its snack and convenience store presence.
- Ticker
- $SJM
- Sector
- Consumer Essentials
- Primary listing
- NYSE
- Employees
- 8,000
- Headquarters
- Orrville, United States
- Website
- www.jmsmucker.com
J.M. Smucker Metrics
BasicAdvanced
$13B
56.18
$2.15
0.26
$4.42
3.71%
Price and volume
Market cap
$13B
Beta
0.26
52-week high
$135.89
52-week low
$88.25
Average daily volume
1.4M
Dividend rate
$4.42
Financial strength
Current ratio
0.87
Quick ratio
0.288
Long term debt to equity
1.112
Total debt to equity
1.207
Dividend payout ratio (TTM)
203.53%
Interest coverage (TTM)
4.68%
Profitability
EBITDA (TTM)
2,248.5
Gross margin (TTM)
37.95%
Net profit margin (TTM)
2.51%
Operating margin (TTM)
18.56%
Effective tax rate (TTM)
45.62%
Revenue per employee (TTM)
$1,140,000
Management effectiveness
Return on assets (TTM)
6.26%
Return on equity (TTM)
3.93%
Valuation
Price to earnings (TTM)
56.18
Price to revenue (TTM)
1.407
Price to book
2.24
Price to tangible book (TTM)
-2.54
Price to free cash flow (TTM)
8.112
Free cash flow yield (TTM)
12.33%
Free cash flow per share (TTM)
14.88
Dividend yield (TTM)
3.66%
Forward dividend yield
3.71%
Growth
Revenue change (TTM)
5.08%
Earnings per share change (TTM)
-115.67%
3-year revenue growth (CAGR)
2.67%
10-year revenue growth (CAGR)
1.78%
3-year earnings per share growth (CAGR)
133.74%
10-year earnings per share growth (CAGR)
-9.88%
3-year dividend per share growth (CAGR)
2.37%
10-year dividend per share growth (CAGR)
4.82%
What the Analysts think about J.M. Smucker
Analyst ratings (Buy, Hold, Sell) for J.M. Smucker stock.
Analyst projections of the future price of J.M. Smucker stock.
Bulls say / Bears say
J.M. Smucker raised fiscal 2027 guidance after a strong first quarter: sales rose 5%, adjusted EPS rose 71%, and the new adjusted EPS range is $10.50–$11.00. It also lifted expected free cash flow to about $1.1 billion. (J.M. Smucker, Reuters)
Uncrustables has become a meaningful growth engine, reaching $1 billion in annual sales and returning to double-digit first-quarter growth. Management has raised its full-year growth outlook for the brand to high single digits, with added plant capacity supporting further expansion. (J.M. Smucker, Stock Analysis)
The balance sheet is improving and gives Smucker more financial flexibility. Management says leverage reached 2.9 times net debt to EBITDA, with at least $500 million of planned debt repayment in fiscal 2027 alongside continued dividends and possible share repurchases. (Stock Analysis, J.M. Smucker)
The sharp first-quarter EPS improvement overstates the underlying recovery because it included about $115 million of tariff refunds. Smucker says the full-year guidance still contains an estimated $0.60 benefit from those refunds, which will not be a recurring operating gain. (J.M. Smucker, Reuters)
The Hostess-led sweet baked snacks business remains a drag. First-quarter sales fell 7%, while convenience-store traffic is still weak and management expects low-single-digit segment declines for the full year. (Food Business News, J.M. Smucker)
Coffee remains a volume and pricing risk despite strong recent sales. Smucker expects lower coffee prices to reduce net price realisation and is using cautious volume assumptions, so fiscal 2027 sales are still forecast to decline 1% to 2%. (Reuters, J.M. Smucker)
Data summarised monthly by Lightyear AI. Last updated on 22 Sept 2026.
J.M. Smucker Financial Performance
Revenues and expenses
J.M. Smucker Earnings Performance
Company profitability
Upcoming events
No upcoming events
J.M. Smucker News
AllArticlesVideos
Funds containing J.M. Smucker
AllEURGBPUSD
Fund name | Fund size | $SJM weighting |
|---|---|---|
SPDR S&P US Dividend Aristocrats€SPYD | €3.3B | 0.54% |
SPDR S&P US Dividend Aristocrats£USDV | £2.8B | 0.54% |
iShares S&P 500 Consumer Staples Sector€2B7D | €450M | 0.44% |
iShares S&P 500 Consumer Staples Sector£ICSU | £386M | 0.44% |
iShares S&P 500 Equal Weight€O4J0 | €4.3B | 0.20% |
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.