Lockheed/$LMT
1D1W1MYTD1Y5YMAX
Capital at risk
About Lockheed
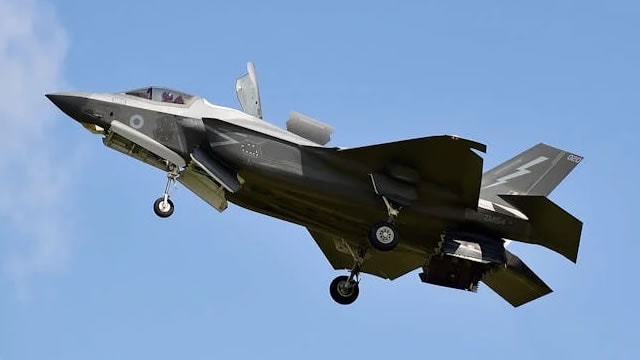
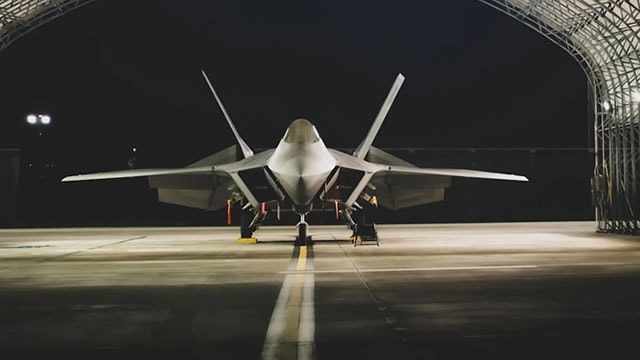
Lockheed Martin is the world's largest defense contractor and has dominated the Western market for high-end fighter aircraft since it won the F-35 Joint Strike Fighter program in 2001. Aeronautics is Lockheed's largest segment, which derives upward of two-thirds of its revenue from the F-35. Lockheed's remaining segments are rotary and mission systems, mainly encompassing the Sikorsky helicopter business; missiles and fire control, which creates missiles and missile defense systems; and space systems, which produces satellites and receives equity income from the United Launch Alliance joint venture.
- Ticker
- $LMT
- Sector
- Industrials
- Primary listing
- NYSE
- Employees
- 123,000
- Headquarters
- Bethesda, United States
- Website
- www.lockheedmartin.com
Lockheed Metrics
BasicAdvanced
$121B
19.25
$27.14
0.10
$13.65
2.64%
Price and volume
Market cap
$121B
Beta
0.1
52-week high
$692.00
52-week low
$437.25
Average daily volume
1.1M
Dividend rate
$13.65
Financial strength
Current ratio
1.193
Quick ratio
0.974
Long term debt to equity
2.342
Total debt to equity
2.342
Dividend payout ratio (TTM)
50.52%
Interest coverage (TTM)
7.55%
Profitability
EBITDA (TTM)
9,746
Gross margin (TTM)
11.80%
Net profit margin (TTM)
8.16%
Operating margin (TTM)
10.89%
Effective tax rate (TTM)
15.28%
Revenue per employee (TTM)
$630,000
Management effectiveness
Return on assets (TTM)
8.64%
Return on equity (TTM)
89.16%
Valuation
Price to earnings (TTM)
19.247
Price to revenue (TTM)
1.565
Price to book
13.7
Price to tangible book (TTM)
-27.83
Price to free cash flow (TTM)
13.808
Free cash flow yield (TTM)
7.24%
Free cash flow per share (TTM)
37.829
Dividend yield (TTM)
2.61%
Forward dividend yield
2.64%
Growth
Revenue change (TTM)
7.20%
Earnings per share change (TTM)
52.49%
3-year revenue growth (CAGR)
4.55%
10-year revenue growth (CAGR)
5.87%
3-year earnings per share growth (CAGR)
-0.29%
10-year earnings per share growth (CAGR)
8.50%
3-year dividend per share growth (CAGR)
4.97%
10-year dividend per share growth (CAGR)
7.78%
What the Analysts think about Lockheed
Analyst ratings (Buy, Hold, Sell) for Lockheed stock.
Analyst projections of the future price of Lockheed stock.
Bulls say / Bears say
Lockheed’s order book reached a record $230 billion after $65 billion of second-quarter orders, giving it unusually strong revenue visibility. Management raised 2026 sales, operating profit and free-cash-flow guidance, signalling confidence that demand is converting into deliveries. (Lockheed Martin)
Missile defence and munitions are becoming a stronger growth engine as the US replenishes stocks and expands production. The $35 billion THAAD agreement and the new framework to accelerate the AIM-260 missile could create years of demand beyond the F-35 programme. (Lockheed Martin, Reuters)
Financial execution improved sharply in the second quarter, with sales up 11%, free cash flow of $2.9 billion and management forecasting more than $7 billion for the full year. That recovery could support dividends and investment while production ramps across the business. (Lockheed Martin)
Lockheed’s fixed-price contracts leave it exposed when inflation, tariffs, supplier shortages or programme delays raise costs. First-quarter profit fell as F-16 and C-130 production problems forced rework and schedule extensions, showing that strong demand does not automatically produce strong margins. (Reuters)
The F-35 remains a major execution risk: estimated acquisition costs have risen by about $51 billion, while Block 4 and Technology Refresh 3 upgrades remain late and over budget. Higher unit prices and weak fleet readiness could invite political scrutiny, slow purchases or pressure Lockheed’s margins. (Breaking Defense, Air & Space Forces Magazine)
Part of the Pentagon’s proposed increase to 85 F-35s for fiscal 2027 depends on a separate reconciliation bill, not the core budget. If Congress does not approve that funding, the purchase could fall to 32 aircraft, creating a sharper near-term demand risk for Lockheed’s largest programme. (Military Times)
Data summarised monthly by Lightyear AI. Last updated on 17 Sept 2026.
Lockheed Financial Performance
Revenues and expenses
Lockheed Earnings Performance
Company profitability
Upcoming events
Lockheed News
AllArticlesVideos
Funds containing Lockheed
AllEURGBPUSD
Fund name | Fund size | $LMT weighting |
|---|---|---|
iShares Global Aerospace & Defence€DFND | €1.6B | 4.60% |
iShares Global Aerospace & Defence£DFND | £1.4B | 4.60% |
iShares S&P 500 Industrials Sector€2B7C | €673M | 2.01% |
iShares S&P 500 Industrials Sector£IISU | £578M | 2.01% |
SPDR S&P US Dividend Aristocrats€SPYD | €3.3B | 1.26% |
Data displayed above is indicative only and its accuracy or completeness is not guaranteed. Actual execution price may vary. Past performance is not indicative of future results. Your return may be affected by currency fluctuations and applicable fees and charges. Capital at risk.
Real-time US market data is sourced from the IEX order book provided by Polygon. After-hours US market data is 15 minutes delayed and may differ significantly from the actual tradable price at market open.